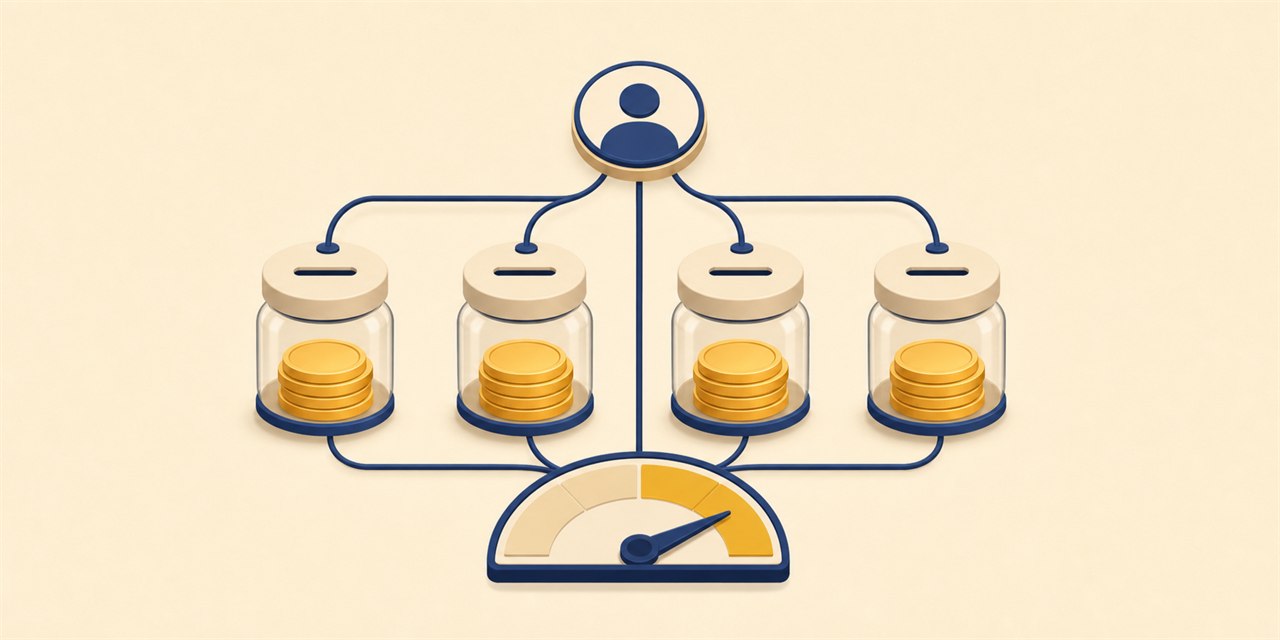
There is no general federal rule limiting a person to one Roth IRA. You might have accounts at several providers, inherit a Roth IRA, or keep separate accounts for investment strategies. The important constraint is that opening more accounts does not multiply the annual contribution limit. Contribution eligibility and limits apply across the owner’s IRAs as the tax rules specify.
This guide provides general education, not individualized tax, legal, investment, or financial advice. Verify current rules and provider procedures for your own facts.
One owner, several account records
Each custodian maintains its own statements, beneficiaries, investments, and tax reporting. The IRS contribution limit, however, is not a per-account allowance. Contributions to traditional and Roth IRAs are coordinated under the annual IRA limit.
The simplest control is a contribution ledger that records date, tax year, account, and amount. Do not rely on one custodian to know what was deposited at another firm.
Reasons to keep accounts separate
Different firms may offer distinct investments, advisory services, cash options, or low-cost funds. Some owners separate a professionally managed account from a self-directed account. Others retain an older account to avoid transfer charges or liquidation of an unavailable asset.
Separate accounts can also support distinct beneficiary designations. That may be useful, but it demands coordination with the broader estate plan because every form must remain current.
Reasons to consolidate
Consolidation can reduce statements, passwords, fees, beneficiary forms, and rebalancing work. A single view also makes it easier to understand total asset allocation and available contribution basis records.
Before consolidating, compare investments and service. Use a direct trustee-to-trustee transfer where appropriate, and preserve statements and contribution history. Consolidation should not erase the evidence needed to understand future distributions.
A practical review process
- Inventory every Roth IRA and custodian. Start with documents and facts rather than assumptions. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Add annual contributions across all traditional and Roth IRAs. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Compare fees, investments, beneficiaries, and services. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Decide whether separation has a defined purpose. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Use direct transfers and retain complete records if consolidating. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
Questions worth asking before you act
Use these questions to test the details behind can you have multiple roth iras:
- What document controls? Determine whether the answer comes from federal tax guidance, the IRA custodial agreement, a brokerage policy, an investment prospectus, or state law. Those sources answer different questions and should not be substituted for one another.
- What event creates tax reporting? Distinguish an internal trade, contribution, transfer, rollover, conversion, correction, and distribution. Similar-looking money movements can produce different forms and deadlines.
- What history must follow the account? Identify contribution basis, conversion years, prior distributions, beneficiaries, and transaction confirmations that a new provider or future tax preparer may not possess.
- What could change before completion? Fees, market prices, settlement status, provider restrictions, filing status, and current-year IRS guidance can all affect the result. Recheck time-sensitive inputs at the point of action.
- Who is qualified to resolve uncertainty? The custodian can explain its process, but it generally cannot provide individualized tax or legal advice. Use a qualified tax professional or attorney when ownership, reporting, or legal rights are unclear.
Worked example
A hypothetical saver contributes through two providers during the same year. The first account receives part of the saver’s permitted amount, and the second receives the remainder. That can be valid; contributing the full annual amount to each would create an excess. The exact allowed contribution depends on the year, compensation, filing status, and modified AGI, so the saver checks the current IRS worksheet before funding either account.
The example is hypothetical and omits taxes, returns, fees, and personal circumstances not stated. It is a framework for identifying questions, not a recommendation.
Common mistakes
- Treating each account as a separate contribution limit. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Losing track of contribution basis. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Duplicating incompatible investment strategies. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Leaving outdated beneficiaries on an old account. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Closing an account before confirming all assets transferred. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
Documentation checklist
A durable file for can you have multiple roth iras should contain the relevant account agreement, annual statements, transaction confirmations, Forms 5498 and 1099-R when issued, filed tax returns that report IRA activity, and correspondence about corrections or transfers. Keep the records in a format you can still access after changing providers.
Use a simple index with the document date, tax year, account, transaction type, and why the record matters. Sensitive retirement documents should be stored securely, with an encrypted backup and appropriate access for a trusted person or fiduciary if your estate plan calls for it.
Documentation does not determine the legal or tax result by itself, but it allows the owner and advisers to reconstruct what happened. That distinction is especially important when a brokerage dashboard displays only current holdings and recent transactions.
Key takeaways
- Each custodian maintains its own statements, beneficiaries, investments, and tax reporting. The IRS contribution limit, however, is not a per-account allowance. Contributions to traditional and Roth IRAs are coordinated under the annual IRA limit.
- Different firms may offer distinct investments, advisory services, cash options, or low-cost funds. Some owners separate a professionally managed account from a self-directed account. Others retain an older account to avoid transfer charges or liquidation of an unavailable asset.
- Consolidation can reduce statements, passwords, fees, beneficiary forms, and rebalancing work. A single view also makes it easier to understand total asset allocation and available contribution basis records.
- Keep durable records and verify current rules before a contribution, transfer, or distribution.
Frequently asked questions
Can I open a new Roth IRA every year?
You can own multiple accounts, but the annual contribution rules still apply across them.
Do transfers count as new contributions?
A properly completed transfer between Roth IRA custodians is generally not an annual contribution.
Does each Roth IRA have its own qualified-distribution five-year period?
The qualified-distribution period is generally measured from the first year for which a contribution was made to any Roth IRA for the owner, but conversion penalty periods have separate rules.
Can accounts have different beneficiaries?
Yes, subject to the custodian’s documents and applicable law. Coordinate the forms intentionally.
Sources and next steps
- [IRS Roth IRA contribution overview](https://www.irs.gov/retirement-plans/roth-iras)
- [IRS contribution limits and trustee-transfer rules](https://www.irs.gov/publications/p590a)
- [IRS Roth distribution ordering and five-year rules](https://www.irs.gov/publications/p590b)
Use the [Roth IRA calculator](/) for a clearly labeled growth illustration and the [Roth IRA contribution calculator](/contribution-calculator) to test contribution scenarios. Then review the related [Roth IRA basics guide](/blog/roth-ira-basics-2026), [opening your first Roth IRA](/blog/opening-first-roth-ira), and the [growth calculator](/growth-calculator) before making account changes.