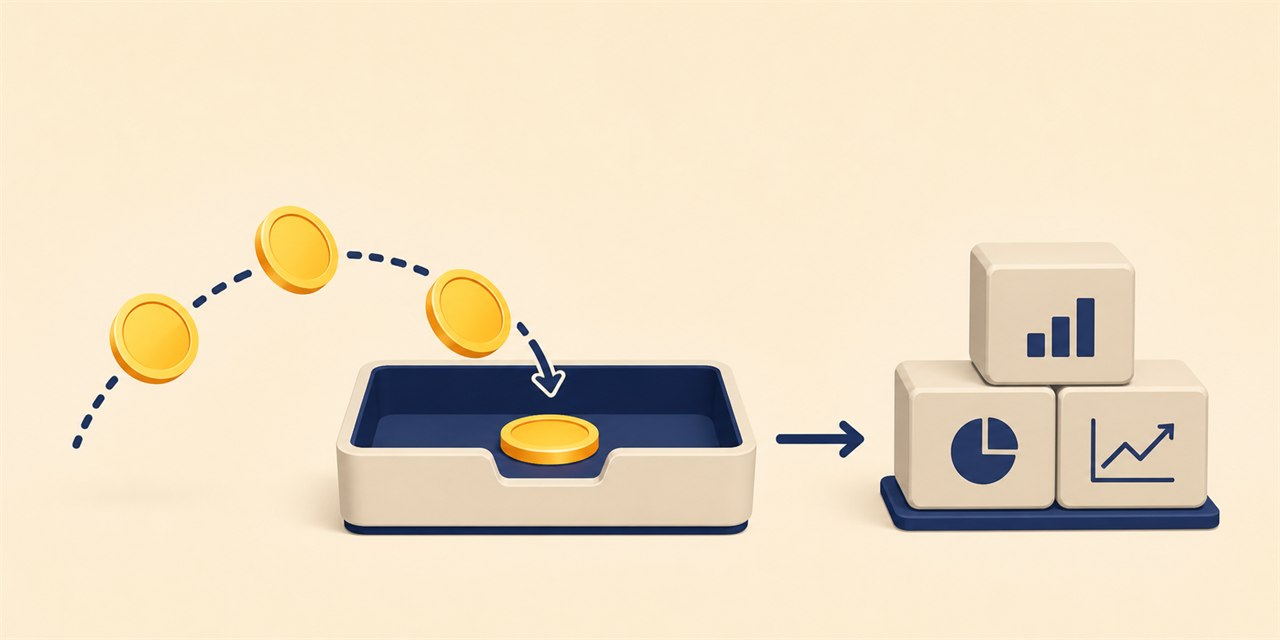
Making a Roth IRA contribution and investing that contribution are two separate actions. At many brokerages, new cash first lands in a settlement fund, core position, sweep account, or similar cash vehicle. Until an investment order is completed, the money may remain in that holding position rather than gaining or losing value with the portfolio you intended to own.
This guide provides general education, not individualized tax, legal, investment, or financial advice. Verify current rules and provider procedures for your own facts.
The path from bank to investment
A contribution begins as a transfer into the Roth IRA. The brokerage records the tax-year designation and credits the account. Cash then sits in the account’s designated core position until it is used to buy an investment. A pending deposit can also be subject to collection or trading restrictions.
The settlement fund is operational plumbing, not a separate IRA. Cash, funds, and securities remain inside the same Roth wrapper. Moving among investments inside the Roth generally does not create current federal income tax.
Settlement and trade timing
When an order executes, the trade date records the transaction and the settlement date marks completion under market rules. Available-to-trade and available-to-withdraw balances can differ. A brokerage may permit trading before deposited funds are fully collected while restricting withdrawals.
Selling an investment reverses the process: proceeds become cash after settlement. A cash balance can then be reinvested, held, or distributed. A distribution out of the IRA is different from a trade inside it and can carry tax-reporting consequences.
The uninvested-cash problem
A saver can contribute faithfully for months while unintentionally leaving every deposit in cash. The account statement will show a Roth balance, but performance will follow the settlement vehicle rather than the intended long-term allocation.
Automation can reduce this risk. Some providers permit recurring investments after recurring deposits; others require a separate order. Verify the workflow instead of assuming that an automatic contribution also purchases a fund.
A practical review process
- Confirm the contribution reached the Roth IRA for the intended tax year. Start with documents and facts rather than assumptions. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Locate the account’s core or settlement position. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Check whether the deposit is collected and available to trade. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Place or schedule the intended investment order. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Review the next statement to confirm the resulting holdings. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
Questions worth asking before you act
Use these questions to test the details behind how roth ira settlement funds work after you make a contribution:
- What document controls? Determine whether the answer comes from federal tax guidance, the IRA custodial agreement, a brokerage policy, an investment prospectus, or state law. Those sources answer different questions and should not be substituted for one another.
- What event creates tax reporting? Distinguish an internal trade, contribution, transfer, rollover, conversion, correction, and distribution. Similar-looking money movements can produce different forms and deadlines.
- What history must follow the account? Identify contribution basis, conversion years, prior distributions, beneficiaries, and transaction confirmations that a new provider or future tax preparer may not possess.
- What could change before completion? Fees, market prices, settlement status, provider restrictions, filing status, and current-year IRS guidance can all affect the result. Recheck time-sensitive inputs at the point of action.
- Who is qualified to resolve uncertainty? The custodian can explain its process, but it generally cannot provide individualized tax or legal advice. Use a qualified tax professional or attorney when ownership, reporting, or legal rights are unclear.
Worked example
Suppose a saver transfers $300 monthly and expects a broad-market fund to grow over time. If the recurring bank transfer is active but the recurring purchase is not, $3,600 accumulates in the settlement position after twelve deposits. No rule was broken, but the portfolio does not match the plan. The correction is operational: choose the investment and confirm future purchases, without treating the internal trade as a new contribution.
The example is hypothetical and omits taxes, returns, fees, and personal circumstances not stated. It is a framework for identifying questions, not a recommendation.
Common mistakes
- Stopping after the bank transfer. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Confusing a cash balance with an invested portfolio. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Withdrawing unsettled proceeds. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Selecting the wrong contribution year. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Ignoring the yield and insurance status of the cash option. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
Documentation checklist
A durable file for how roth ira settlement funds work after you make a contribution should contain the relevant account agreement, annual statements, transaction confirmations, Forms 5498 and 1099-R when issued, filed tax returns that report IRA activity, and correspondence about corrections or transfers. Keep the records in a format you can still access after changing providers.
Use a simple index with the document date, tax year, account, transaction type, and why the record matters. Sensitive retirement documents should be stored securely, with an encrypted backup and appropriate access for a trusted person or fiduciary if your estate plan calls for it.
Documentation does not determine the legal or tax result by itself, but it allows the owner and advisers to reconstruct what happened. That distinction is especially important when a brokerage dashboard displays only current holdings and recent transactions.
Key takeaways
- A contribution begins as a transfer into the Roth IRA. The brokerage records the tax-year designation and credits the account. Cash then sits in the account’s designated core position until it is used to buy an investment. A pending deposit can also be subject to collection or trading restrictions.
- When an order executes, the trade date records the transaction and the settlement date marks completion under market rules. Available-to-trade and available-to-withdraw balances can differ. A brokerage may permit trading before deposited funds are fully collected while restricting withdrawals.
- A saver can contribute faithfully for months while unintentionally leaving every deposit in cash. The account statement will show a Roth balance, but performance will follow the settlement vehicle rather than the intended long-term allocation.
- Keep durable records and verify current rules before a contribution, transfer, or distribution.
Frequently asked questions
Is a settlement fund part of my Roth IRA?
Yes, when held inside the account. It is a cash position within the Roth wrapper.
Does contributing automatically buy investments?
Not always. Provider workflows differ, so confirm whether a separate purchase instruction is required.
Is settlement-fund interest taxable each year?
Income earned inside a Roth IRA is generally not reported as current taxable income, although distribution rules still apply.
Can I change investments without withdrawing?
Buying and selling inside the Roth is different from taking a distribution out of the account.
Sources and next steps
- [FINRA overview of brokerage account operations](https://www.finra.org/investors/investing/investment-accounts/brokerage-accounts)
- [IRS overview of Roth tax treatment](https://www.irs.gov/retirement-plans/roth-iras)
- [IRS contribution and transfer rules](https://www.irs.gov/publications/p590a)
Use the [Roth IRA calculator](/) for a clearly labeled growth illustration and the [Roth IRA contribution calculator](/contribution-calculator) to test contribution scenarios. Then review the related [Roth IRA basics guide](/blog/roth-ira-basics-2026), [opening your first Roth IRA](/blog/opening-first-roth-ira), and the [growth calculator](/growth-calculator) before making account changes.