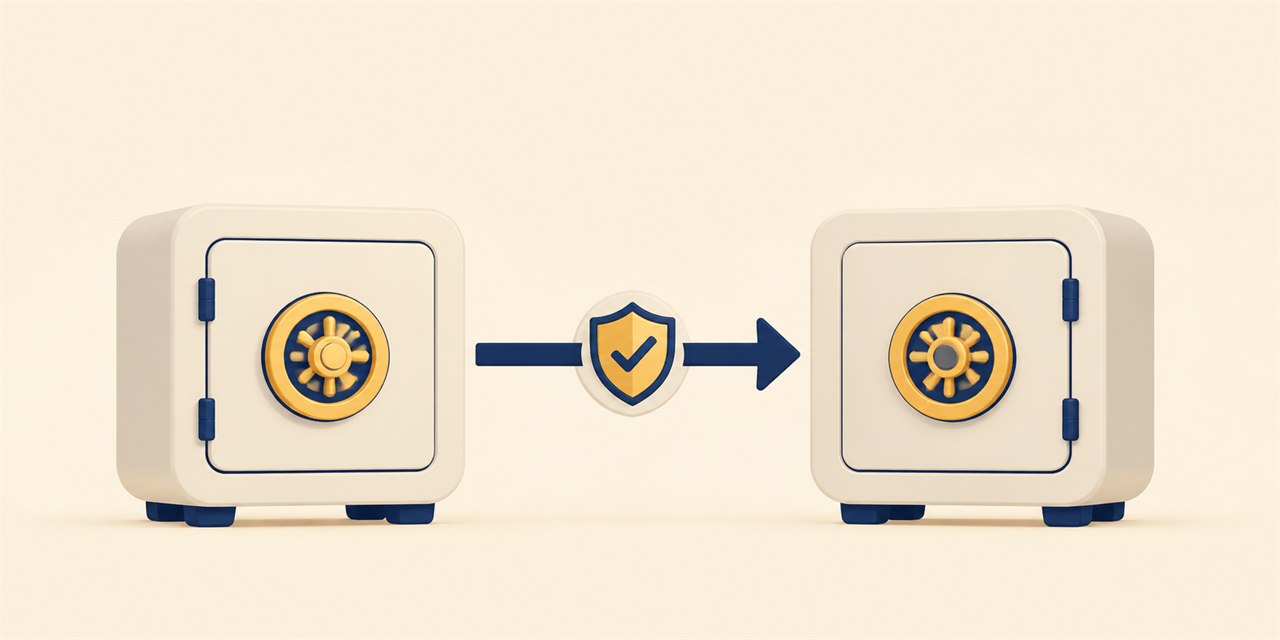
Moving a Roth IRA between brokerages can lower costs, simplify accounts, or provide better investments. The safest routine approach is usually a direct trustee-to-trustee transfer initiated through the receiving firm. That keeps the assets inside the retirement-account system and avoids making the owner responsible for redepositing a distribution on time.
This guide provides general education, not individualized tax, legal, investment, or financial advice. Verify current rules and provider procedures for your own facts.
Direct transfer versus rollover
In a direct trustee-to-trustee transfer, the owner does not receive the assets personally. IRS Publication 590-A explains that a trustee transfer is not a rollover and is not subject to the once-per-year IRA rollover waiting rule.
A 60-day rollover begins with a distribution to the owner and adds deadlines, withholding questions, and the risk of an incomplete redeposit. It can be valid, but it is usually unnecessary for an ordinary brokerage change.
In-kind and cash transfers
An in-kind transfer moves supported securities without selling them. A cash transfer liquidates holdings first or transfers an existing cash balance. Selling inside the Roth does not by itself create current capital-gain tax, but liquidation can create market-timing risk, fund charges, or time out of the market.
FINRA notes that receiving firms can reject nontransferable assets, including some proprietary products. Ask the new brokerage to review holdings before submitting the request.
How the transfer process works
The owner opens a matching Roth IRA at the receiving firm and submits its transfer form with current account details. Broker-dealers commonly use ACATS. FINRA says properly matched common assets generally move through validation and delivery, while IRA custody and non-broker custodians can require additional time.
After delivery, compare positions, cash, cost information, and residual dividends. Fractional shares may be liquidated and arrive later. Keep both firms’ final statements.
A practical review process
- Open a Roth IRA with matching ownership at the receiving firm. Start with documents and facts rather than assumptions. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Ask whether every holding can transfer in kind. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Initiate the request through the receiving brokerage. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Avoid trading while the transfer is pending unless both firms approve. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
- Reconcile assets, residual cash, beneficiaries, and statements after completion. Record the result so the next decision is based on a complete account history. Ask the provider to confirm its answer in writing, note the date of the confirmation, and save the relevant statement, form, or fee schedule. If the answer depends on a tax year or a pending transaction, identify that dependency explicitly before moving money.
Questions worth asking before you act
Use these questions to test the details behind how to transfer a roth ira between brokerages without tax trouble:
- What document controls? Determine whether the answer comes from federal tax guidance, the IRA custodial agreement, a brokerage policy, an investment prospectus, or state law. Those sources answer different questions and should not be substituted for one another.
- What event creates tax reporting? Distinguish an internal trade, contribution, transfer, rollover, conversion, correction, and distribution. Similar-looking money movements can produce different forms and deadlines.
- What history must follow the account? Identify contribution basis, conversion years, prior distributions, beneficiaries, and transaction confirmations that a new provider or future tax preparer may not possess.
- What could change before completion? Fees, market prices, settlement status, provider restrictions, filing status, and current-year IRS guidance can all affect the result. Recheck time-sensitive inputs at the point of action.
- Who is qualified to resolve uncertainty? The custodian can explain its process, but it generally cannot provide individualized tax or legal advice. Use a qualified tax professional or attorney when ownership, reporting, or legal rights are unclear.
Worked example
Assume a Roth IRA holds three widely traded ETFs and a proprietary mutual fund. The new firm accepts the ETFs but not the proprietary fund. The owner can evaluate whether to retain a partial account, exchange the unsupported holding inside the Roth before transfer, or use another receiving firm. The tax wrapper does not eliminate investment and timing consequences, so the choice should be made before the transfer begins.
The example is hypothetical and omits taxes, returns, fees, and personal circumstances not stated. It is a framework for identifying questions, not a recommendation.
Common mistakes
- Withdrawing a check payable personally without understanding rollover rules. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Closing the old account too early. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Assuming proprietary funds will transfer. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Forgetting fractional shares and residual dividends. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
- Discarding contribution and conversion records. Pause and confirm the governing document, current IRS guidance, and the provider’s written procedure before acting. Write down the assumption that led to the mistake, because that makes it easier to design a checklist that prevents the same error later.
Documentation checklist
A durable file for how to transfer a roth ira between brokerages without tax trouble should contain the relevant account agreement, annual statements, transaction confirmations, Forms 5498 and 1099-R when issued, filed tax returns that report IRA activity, and correspondence about corrections or transfers. Keep the records in a format you can still access after changing providers.
Use a simple index with the document date, tax year, account, transaction type, and why the record matters. Sensitive retirement documents should be stored securely, with an encrypted backup and appropriate access for a trusted person or fiduciary if your estate plan calls for it.
Documentation does not determine the legal or tax result by itself, but it allows the owner and advisers to reconstruct what happened. That distinction is especially important when a brokerage dashboard displays only current holdings and recent transactions.
Key takeaways
- In a direct trustee-to-trustee transfer, the owner does not receive the assets personally. IRS Publication 590-A explains that a trustee transfer is not a rollover and is not subject to the once-per-year IRA rollover waiting rule.
- An in-kind transfer moves supported securities without selling them. A cash transfer liquidates holdings first or transfers an existing cash balance. Selling inside the Roth does not by itself create current capital-gain tax, but liquidation can create market-timing risk, fund charges, or time out of the market.
- The owner opens a matching Roth IRA at the receiving firm and submits its transfer form with current account details. Broker-dealers commonly use ACATS. FINRA says properly matched common assets generally move through validation and delivery, while IRA custody and non-broker custodians can require additional time.
- Keep durable records and verify current rules before a contribution, transfer, or distribution.
Frequently asked questions
Does a direct Roth IRA transfer create tax?
A properly completed trustee-to-trustee transfer generally is tax free and is not treated as a distribution to the owner.
How long does a brokerage transfer take?
FINRA says common broker-to-broker transfers often take several business days after validation, while IRA or nonstandard transfers may take longer.
Can I transfer only part of a Roth IRA?
Many custodians permit partial transfers, subject to their forms, minimums, and asset restrictions.
Will my beneficiary form transfer too?
Usually not. Complete and verify beneficiary designations at the receiving custodian.
Sources and next steps
- [IRS rules for trustee transfers and rollovers](https://www.irs.gov/publications/p590a)
- [FINRA ACATS process and transfer timing](https://www.finra.org/investors/investing/investment-accounts/brokerage-accounts)
- [IRS Roth IRA overview](https://www.irs.gov/retirement-plans/roth-iras)
Use the [Roth IRA calculator](/) for a clearly labeled growth illustration and the [Roth IRA contribution calculator](/contribution-calculator) to test contribution scenarios. Then review the related [Roth IRA basics guide](/blog/roth-ira-basics-2026), [opening your first Roth IRA](/blog/opening-first-roth-ira), and the [growth calculator](/growth-calculator) before making account changes.